Turn Your Inventory
Into
Working Capital.
Finance
Equipment.
Fuel Growth.

Big‐Business Inventory Financing. Built for Small Business.

We're one of the few places to find revolving inventory lines of credit
from $2 Million to $10 Million, giving small businesses access
to financing normally reserved for large corporate interests.

What Sets Us Apart?

$2 Million to $10 Million
Reusable credit facilities scaled to inventory asset value, not your receivables.
Accommodative Loan Sizes
Enterprise-grade financing, engineered for businesses at many stages of growth.
Flexible Structures
Tailored solutions for your unique inventory profile and operational demands.
Deep Expertise
A proven network with decades of asset-based lending experience.
Prefer to talk it through? 1-888-709-4664
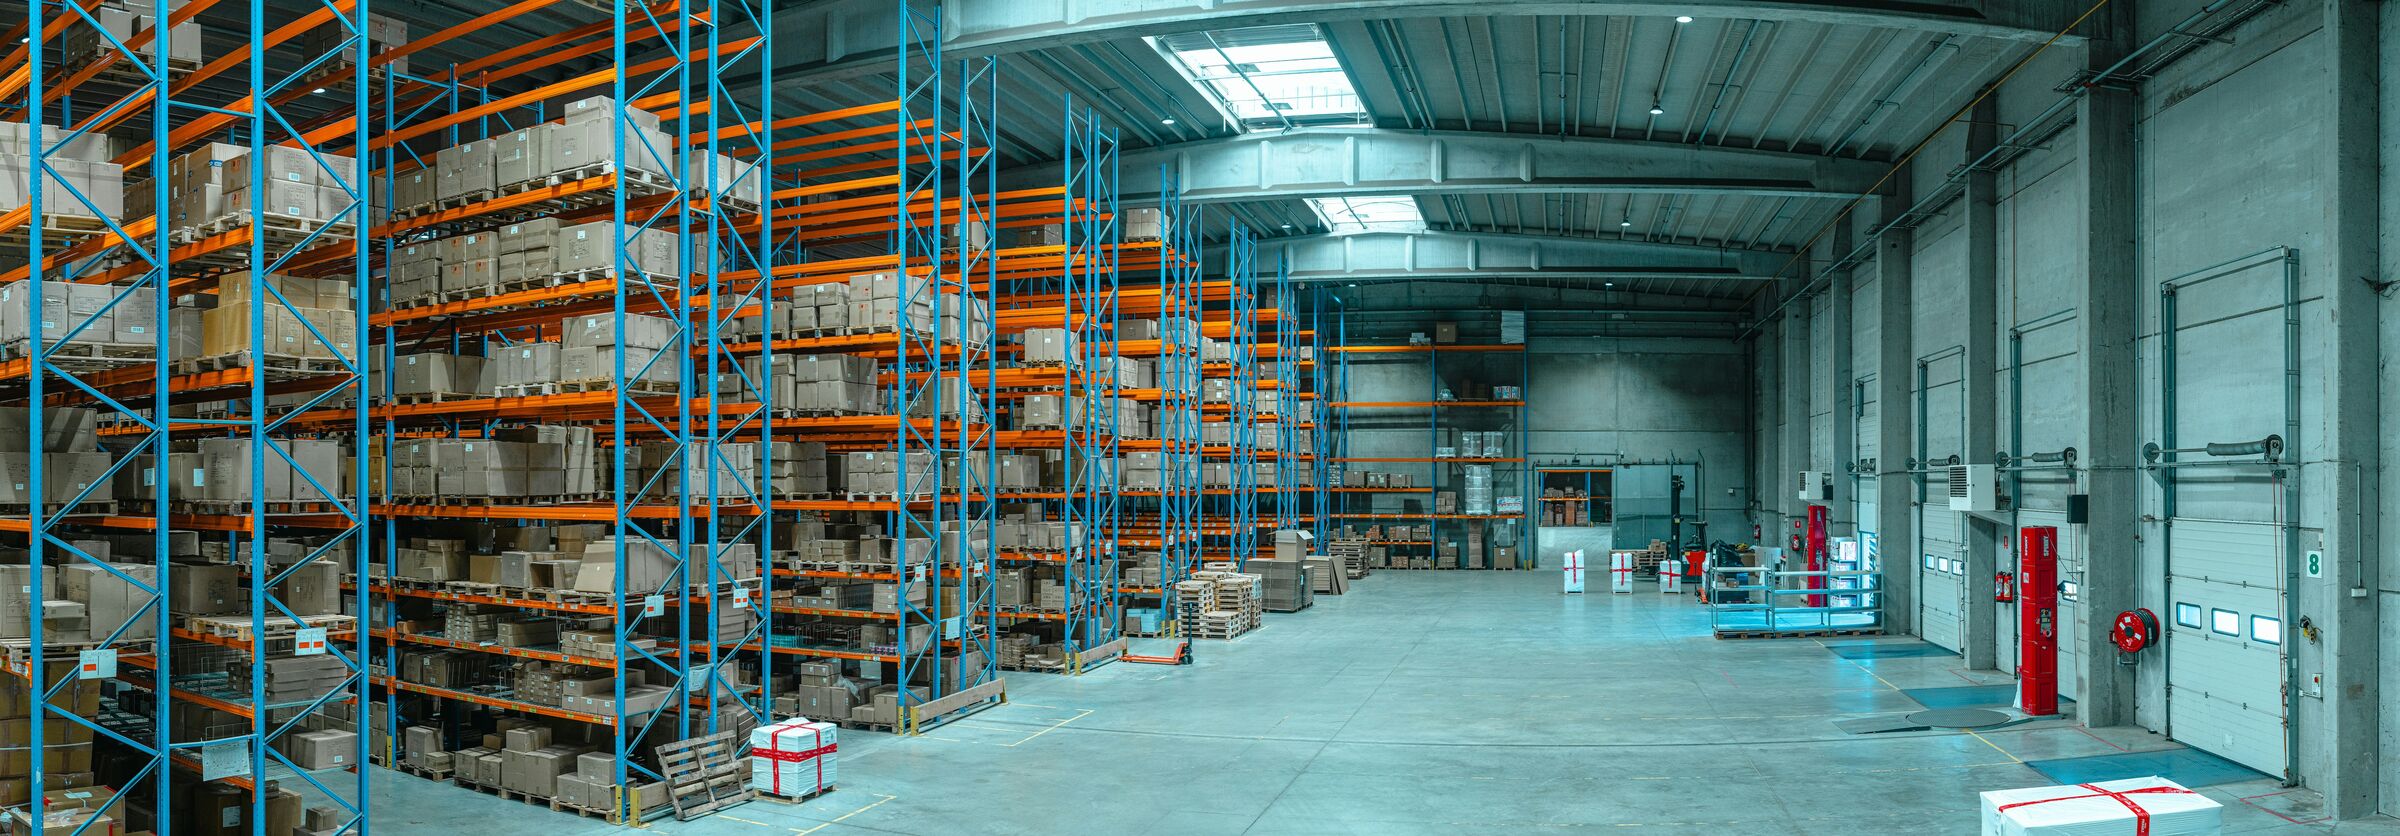
Pallets of packaged stock stacked in a distribution warehouse

Lending Products Built to Work for You

Many lenders won't show rates and fees until you apply. Each product page shows them upfront because transparency respects your time. Your lender sets the final terms in your financing agreement.

Inventory Line of Credit

$2 Million to $10 Million

A revolving line of credit backed by the value of your saleable inventory - on your shelves, in a warehouse, or at an Amazon FBA facility.

  • Typically no credit pull or personal guarantee
  • 50% to 80% of inventory cost
  • Pay interest only on what you draw
Learn More

Short-Term Small Business Loan

$10 Thousand to $1.5 Million

A lump-sum loan collateralized by future receivables, with no hard assets pledged.

  • Get your funds in as little as 24 hours
  • 6 to 24 month terms
  • Fixed weekly or monthly payments
Learn More

Business Line of Credit

$10 Thousand to $500 Thousand

A revolving line of credit for business owners who want capital fast, without pledging hard assets.

  • Get your funds in as little as 24 hours
  • Draw and re-draw as you need it
  • Collateralized by future receivables
Learn More

Equipment Financing & Leasing

$10 Thousand to $5 Million

The equipment your business needs is the collateral - financed or leased over terms up to 5 years.

  • Approvals often come in 24 to 48 hours
  • 2 to 5 year terms, fixed monthly payments
  • Usually closes in 1 to 3 weeks
Learn More

Who Is This For?

Our lending partners can say yes where banks say no. Our inventory line of credit customers are often ineligible for traditional bank loans for a variety of reasons:

Less than 3 years in business
Operating losses
Low net worth
High debt-to-equity ratio
Profitability concerns
Issues with personal credit
Being out of covenant or asked to leave their bank
Irregular or negative cash flow
Automated cart moving assembled wire harnesses on a factory floor

What Can You Do With This Funding?

The flagship product we arrange, an Inventory Line of Credit, turns your saleable inventory into working capital, whether it's on your shelves, in a warehouse, or at an Amazon FBA facility. Use it to:

  • Replenish inventory
  • Buy out partners or competitors
  • Bridge seasonal cash flow gaps
  • Launch new products or expand
  • Stay current with suppliers and vendors
  • Support turnarounds without sacrificing momentum
  • Swap costly daily payments for repayment as inventory sells
  • Eliminate expensive merchant cash advances

Funding That Moves at Your Speed

1

Apply Now

Applying is free and commits you to nothing. Send the short form or call us, and a lending specialist will be in touch within one business day.

2

Go Through Underwriting

We connect you with private lenders, not banks bound by rigid lending rules, so underwriting is more flexible.

3

Receive Your Funds

Short-term loans and business lines of credit can fund in as little as 24 hours. Equipment financing usually closes in 1 to 3 weeks. Inventory lines typically take a month or more to close due to the need for an independent appraisal.

Packaged inventory boxes staged in a warehouse, ready to ship
Apply Now

This Is Not One‐Size‐Fits‐All Financing

Our inventory lines of credit are tailor-made for businesses like:

Racks of colorful shirts in a retail clothing store

Retailers

If your capital is tied up in fast-turning or seasonal stock, and banks aren't keeping up, our lending partners can.

  • Small-to-midsize stores
  • Inventory-heavy businesses
  • Bridge or growth-stage financing needs
Packed orders staged for shipment in a fulfillment warehouse

E-Commerce Brands

Selling direct to customers, or on platforms like Amazon or Shopify? We help turn warehouse stock into working capital.

  • Fulfillment-heavy businesses
  • High-growth online sellers
  • Younger inventory-focused businesses
Finished goods moving along a manufacturing line

Wholesalers & Manufacturers

Already using accounts receivable lines or factoring? Let us unlock the power of your inventory too.

  • Seasonal or bulk stock builds
  • Raw materials to finished goods
  • Pairs with receivables financing

If You're a U.S. or Canadian Company Seeking a Smarter Way to Finance Growth, Expansion, or Stability, Let's Talk!

Whether you're managing seasonal peaks, launching a new product, or navigating volatility, we have funding options that can help.

FAQs

Most of what business owners ask before applying - who qualifies, how much you can borrow, and how the process works - is answered below. If anything is still unclear, we're happy to talk it through.

Does working with MerchandiseLending.com cost me anything?

Not a cent. Our lending partners pay for our service out of the fees they already charge, so your rate and fees are exactly the same as if you went to the lender directly, never higher. What you gain is a lending specialist in your corner who knows which lending programs say yes to businesses like yours, helps prepare your application, and matches you with the program that fits, so you don't have to search on your own. Your lender makes the final credit decision and is named in your financing agreement.

How much money can my business borrow?

Financing runs from $10 Thousand to $10 Million, depending on the product: short-term loans from $10 Thousand to $1.5 Million, business lines of credit from $10 Thousand to $500 Thousand, equipment financing from $10 Thousand to $5 Million, and inventory lines of credit from $2 Million to $10 Million. Short-term loans and business lines of credit are generally sized at 10% to 15% of gross annual revenue.

Does applying affect my credit score?

Usually not. Inventory line of credit applications typically don't involve a credit pull, though a lender may still run one. Applying for a short-term loan or business line of credit uses only a soft pull, which doesn't affect your score. On some larger equipment financing deals a lender may run a hard pull, but only after you've been approved and chosen to move forward, and always with notice first.

Who is this financing for?

Our inventory lines of credit are built for retailers, e-⁠commerce brands, wholesalers, and manufacturers that carry saleable inventory. Short-term loans, business lines of credit, and equipment financing are open to a wide range of established businesses. Lenders do restrict some industries, so if you're unsure whether yours qualifies, your lending specialist can tell you right away.

What happens after I apply?

A lending specialist will be in touch within one business day to talk through your goals and match you with the right lending program. From there:

Inventory lines of credit: you'll send your application and financials, and the lender typically responds with a term sheet within a couple of days. Once you sign it, underwriting begins, including an independent appraisal and field exam of your inventory. Upfront fees of about $35,000 apply only to inventory lines of credit and cover legal work, due diligence, the appraisal and field exam, and UCC filings; the other products have their own fees, shown on each product page. Closing typically takes a month or more.

Short-term loans and business lines of credit: you'll see the amount, term, and payment before you sign anything. Decisions often come the same day, and funding can follow in as little as 24 hours.

Equipment financing: approvals often come in 24 to 48 hours, the lender pays your equipment vendor directly, and deals usually close in 1 to 3 weeks.

What documents will I need?

It depends on the product. You'll receive a checklist of exactly what's needed, and your lending specialist will help you through the process from start to finish.

Inventory lines of credit: because these are larger facilities, lenders look more closely. Expect to provide a detailed inventory report by item and cost (in Excel), your year-end financial statements for the last three years (or for as long as you've been in business), year-to-date financials compared with the same period last year, 12-month projections, current receivable and payable agings, and a personal financial statement for each owner of 20% or more.

Short-term loans and business lines of credit: usually just a short online application, your last four months of business bank statements, and ID verification.

Equipment financing: for smaller purchases, usually just a one-page application and your equipment invoice, quote, or bill of sale. Larger requests may call for tax returns or financial statements.

See All FAQs

Accelerate Growth. Unlock the Capital (and Opportunity) in Your Inventory.

Contact us today to learn how a credit facility that grows with your inventory can set you on the path to success.

Long warehouse aisle between tall racks of wrapped inventory